Mobile appFintech & paymentsOriginal by Akbank
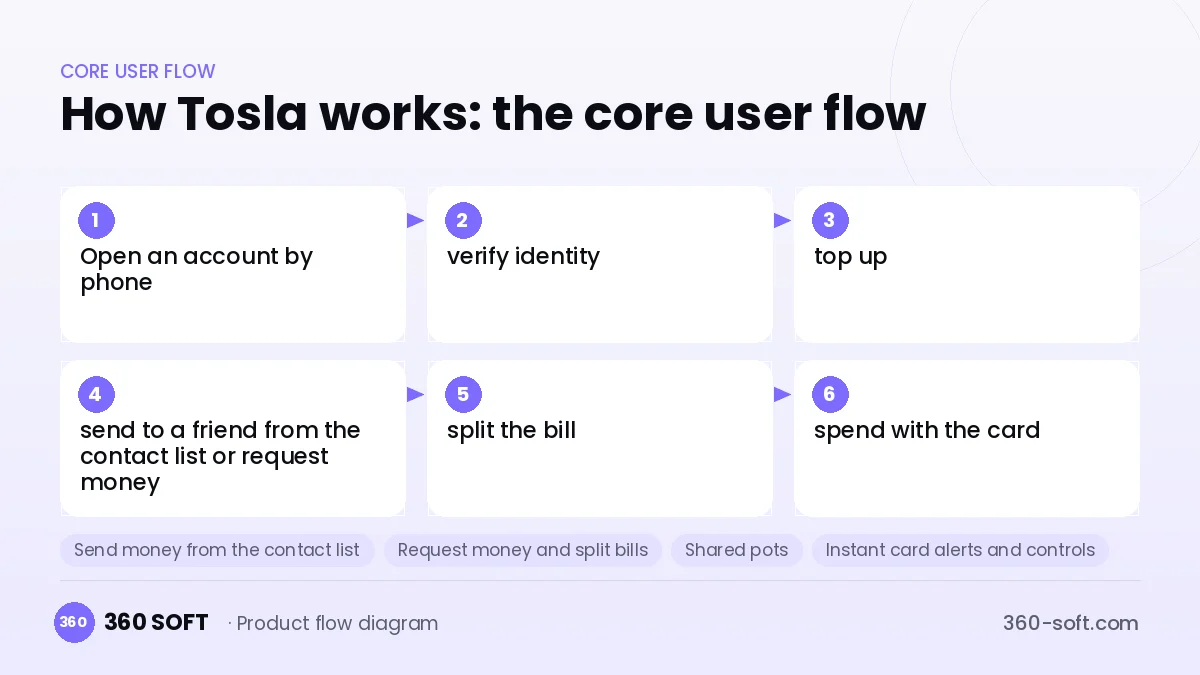
The goal of Tosla, a Turkish digital wallet backed by a major bank, is to give young users just starting their financial lives a simple, fun and social money experience. An account opens in a few steps, sending money to friends is as easy as messaging, shared expenses are split, and card spending arrives as instant notifications. A bank's backing combined with an interface that speaks to a young audience creates both trust and a daily-use habit.
For something similar the legal framework must be settled first: e-money and payment services require a licence from the national regulator, and partnering with a bank or a licensed payment institution is the most common route. Technically you need to build a mobile wallet with strong social features, modules for finding friends from the contact list, requesting money and splitting bills, prepaid card integration, eKYC, transaction monitoring and an operations panel that manages limits suited to young people.
How Tosla works: the core user flow
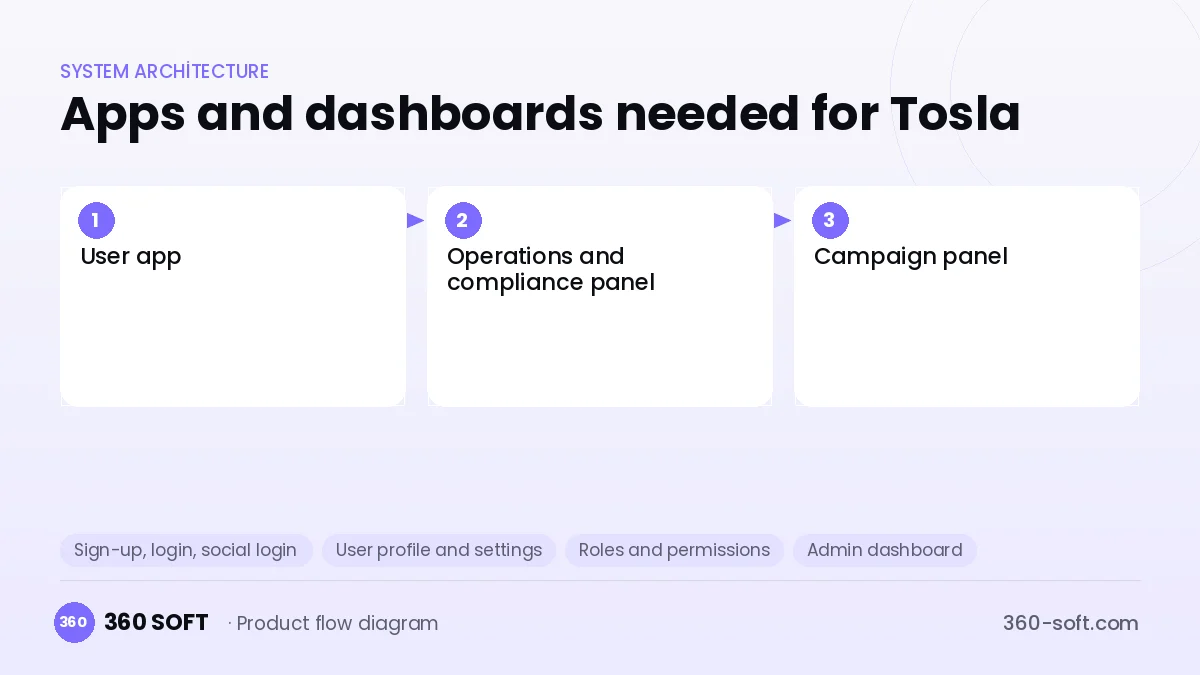
How many apps and dashboards do you need?
User app
Young users top up, send money to friends, split shared expenses and manage their cards.
Operations and compliance panel
The team manages identity checks, age-based limits, suspicious transactions and regulatory notifications.
Campaign panel
The marketing team sets up brand partnerships, cashback campaigns and referral rewards.
Critical features of a product like Tosla
Send money from the contact list
Registered users in the phone contacts are listed, and transfers complete in seconds with an amount, note and emoji.
Request money and split bills
A user shares an expense among friends, and the system sends each person a request and tracks who has paid.
Shared pots
Joint savings pots are created where several people contribute towards a holiday or a gift.
Instant card alerts and controls
Every purchase is notified at once; the card is frozen with one tap, and online and foreign use are switched on and off separately.
Age-appropriate limits
Different limits, approvals and parental consent rules apply to minors and adults in line with regulation.
Referral and cashback campaigns
Rewards for inviting friends and cashback campaigns at partner brands are managed with a rules engine.
What goes into the first version, what comes later
First version (MVP)
- Phone sign-up, eKYC and age-based limits
- Balance top-up and instant transfers from the contact list
- Requesting money and simple bill splitting
- A virtual card and instant notifications on licensed infrastructure
- Operations panel and transaction monitoring
Later releases
- A physical card and card personalisation
- Shared pots and savings goals
- Cashback and brand campaigns
- Bill payments and merchant payments by QR
Modules and how the budget is calculated
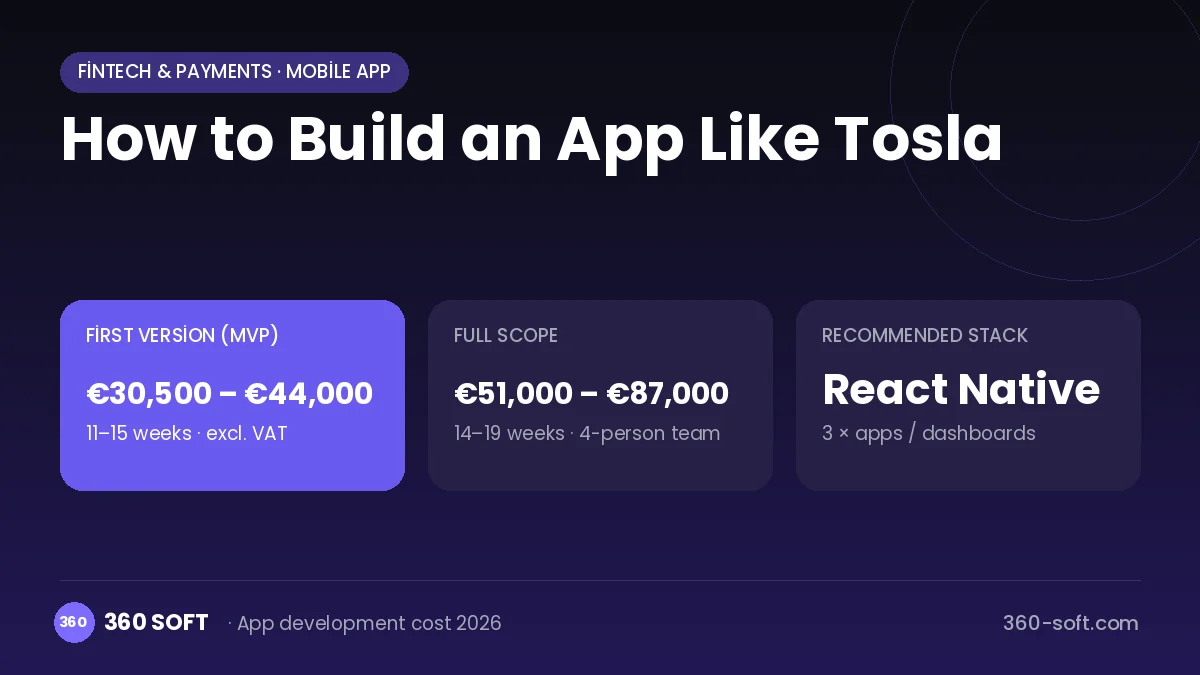
The budget is calculated with 360 SOFT’s pricing model from the modules below, about 32 screens and the project’s complexity: roughly 196 person-days for the full scope and 116 person-days for the first version. Every module you drop lowers the budget directly.
| Module | Phase |
|---|---|
| Sign-up, login, social login | First version |
| User profile and settings | First version |
| Roles and permissions | First version |
| Admin dashboard | First version |
| Online payments (Stripe / PSP) | First version |
| Push notifications | First version |
| Email / SMS notifications | First version |
| Real-time messaging | First version |
| Reporting and analytics | Later release |
| GDPR and security hardening | First version |
| Third-party API integration | First version |
| Barcode / RFID / handheld | Later release |
Hosting, SMS, map APIs, app store accounts and payment-provider fees are separate items. Maintenance and improvements (optional): €650 / month. We send a fixed written price within 24 hours after a free discovery call.
The hard parts
Regulation and bank partnership
Licence requirements and the partner bank's security standards shape the architecture; integration and audit processes can take a long time.
Young users and fraud
Young audiences are more exposed to social engineering; suspicious-recipient warnings, transfer delays and behavioural monitoring matter.
Privacy in social features
Contact matching and friend lists must be designed with explicit consent and data minimisation under GDPR.
Business model
Basic transfers are kept free to win users; revenue comes from interchange on card spending, paid card designs, ATM and foreign-transaction fees, and campaign and sponsorship deals with brands. Later, premium plans for young people, savings products and referrals to the partner bank's products add further income.
Get a free quote for your project
Let us scope it together and send a fixed written quote within 24 hours. NDA on request; you own the source code.
Choosing a company to build an app like Tosla
Most people searching “build an app like tosla” are really looking for a reliable app development company. When comparing quotes, check four things:
- Can you try similar products they have shipped, in the stores or live?
- Are the source code, design files, servers and store accounts transferred to you by contract?
- Do they show a working demo every two weeks, with written scope and acceptance criteria?
- Are maintenance, scaling and GDPR/security costs written into the quote?
Copyright and trademarks
A business model and features are generally not protected on their own, but the Tosla name, logo, interface design, content and source code are. That is why we build a product with similar functionality but your own brand, design and code. This is not legal advice; we recommend a trademark search before launch.
Frequently asked questions
How long does it take to build an app like Tosla?
The mobile app and panels can be built within a few months; integration with a licensed partner, security tests and audits are the steps that really stretch the schedule.
Can this product be built without a bank?
Payment services and e-money require a licence from the national regulator. Without one, you can partner with a bank or licensed payment institution and offer the product on their infrastructure.
Will there be copyright or trademark issues?
The social wallet business model is free to use, but the name, logo, card design, interface and code cannot be copied. This is general information, not legal advice.
What should I look for in a fintech development company?
Choose a team with experience in bank integration, secure mobile development and transaction monitoring. Ask about their independent penetration testing and code security processes.