Mobile appFintech & paymentsOriginal by Intuit
Mint set out a model that automates personal finance by gathering all accounts on one screen. Users link their bank, credit card and investment accounts; transactions arrive on their own, are sorted into categories and are compared with the budget. Not needing manual entry reduces the abandonment that is the biggest problem for budgeting apps. Bill reminders and net-worth tracking complete the picture.
To build something similar, beyond the mobile and web app, the most critical piece is the account-aggregation infrastructure. You develop bank transaction retrieval, a smart categorisation engine, budgets and goals, bill and subscription detection, a net-worth chart and a notification system. Accessing bank data is an account-information service under open banking rules (such as PSD2 in Europe or similar regimes elsewhere), so you need regulated authorisation or a licensed provider.
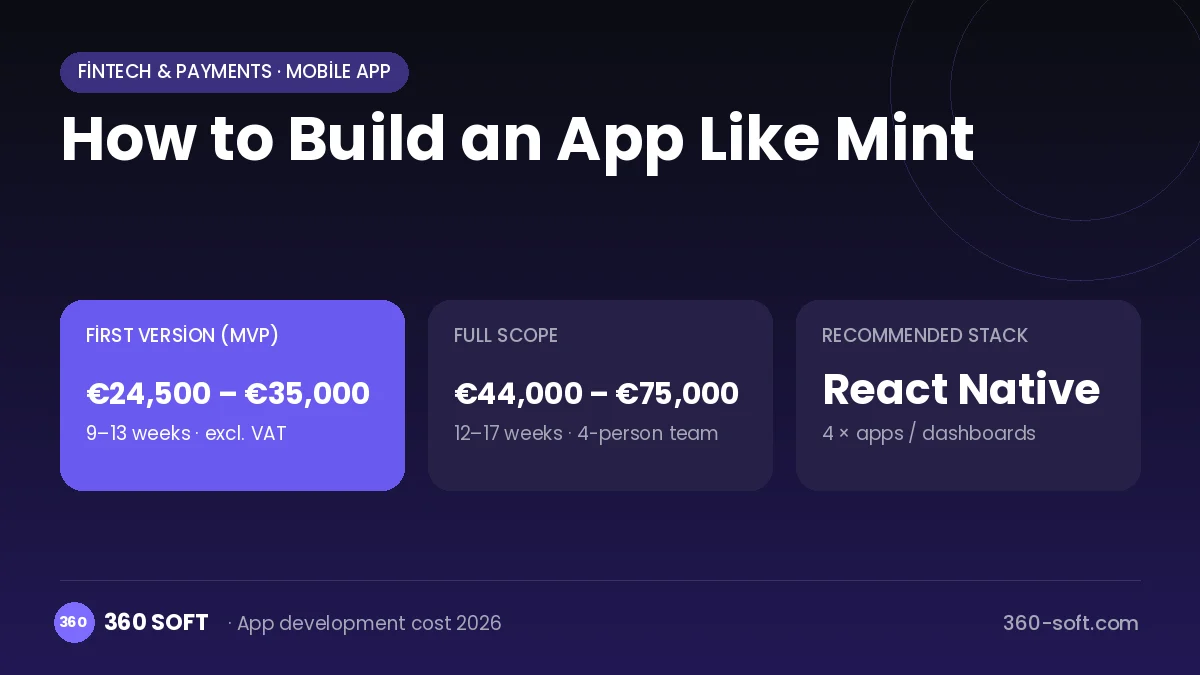
How Mint works: the core user flow
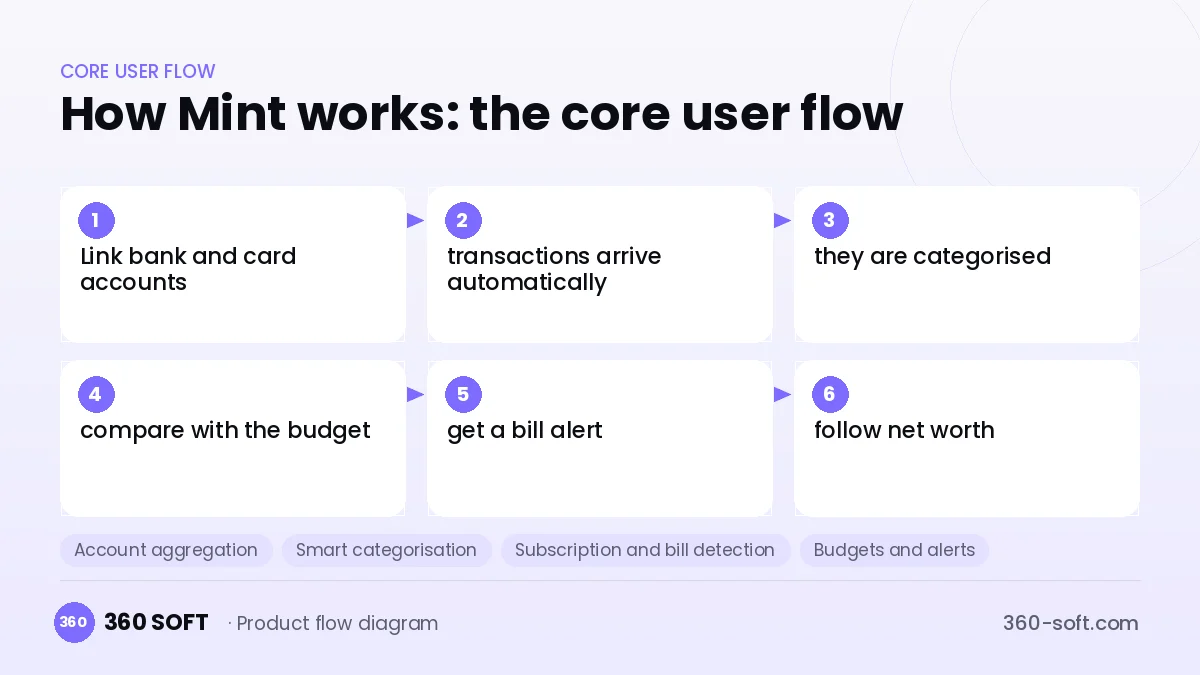
How many apps and dashboards do you need?
Mobile app
The main user app showing account balances, the transaction feed, budgets and notifications.
Web interface
A desktop version for detailed reports, category rules and goal planning.
Data aggregation service
A backend that pulls account and transaction data from an open banking provider and normalises it.
Admin panel
A panel for managing connection errors, category models, offers and user support.
Critical features of a product like Mint
Account aggregation
Current accounts, credit cards and loans from several banks are combined on one screen.
Smart categorisation
Transaction descriptions are sorted into categories such as groceries, transport and rent using rules and machine learning.
Subscription and bill detection
Recurring payments are found automatically, and upcoming dates and price increases are notified.
Budgets and alerts
Real-time alerts are sent for category limits, unusual spending and low balances.
Net-worth tracking
Assets and debts are charted over time, showing how the overall financial position changes.
Goal planning
A monthly saving amount is calculated for goals such as a holiday or a house deposit, and progress is tracked.
What goes into the first version, what comes later
First version (MVP)
- Linking bank accounts through a licensed provider
- Transaction feed and automatic categorisation
- Monthly budget and category limits
- Low-balance and large-spend alerts
- Balance and spending summary screen
Later releases
- Subscription and bill detection
- Net worth and investment account tracking
- Goal planning
- Personalised financial product recommendations
Modules and how the budget is calculated
The budget is calculated with 360 SOFT’s pricing model from the modules below, about 26 screens and the project’s complexity: roughly 169 person-days for the full scope and 93 person-days for the first version. Every module you drop lowers the budget directly.
| Module | Phase |
|---|---|
| Sign-up, login, social login | First version |
| User profile and settings | First version |
| Admin dashboard | First version |
| Subscriptions and recurring billing | First version |
| Push notifications | First version |
| Email / SMS notifications | First version |
| Reporting and analytics | Later release |
| GDPR and security hardening | First version |
| Third-party API integration | First version |
| AI features (LLM, RAG, recommendations) | Later release |
Hosting, SMS, map APIs, app store accounts and payment-provider fees are separate items. Maintenance and improvements (optional): €550 / month. We send a fixed written price within 24 hours after a free discovery call.
The hard parts
Licensing and data access
Accessing bank data requires an authorised account-information service; the duration and renewal of access consents must be managed.
Categorisation accuracy
Bank descriptions are messy and inconsistent, and a wrong category quickly erodes user trust.
Security and privacy
Because a user's whole financial life is gathered in one place, encryption, access control and GDPR compliance must be at the highest level.
Business model
In this model, revenue usually comes from referral commissions on credit card, loan or deposit offers matched to the user's spending profile. A premium subscription offering an ad-free experience, advanced reports and goal planning is the second line. Recommendations must be neutral and clearly labelled for trust. The free tier should stay generous so the user base grows quickly.
Get a free quote for your project
Let us scope it together and send a fixed written quote within 24 hours. NDA on request; you own the source code.
Choosing a company to build an app like Mint
Most people searching “build an app like mint” are really looking for a reliable app development company. When comparing quotes, check four things:
- Can you try similar products they have shipped, in the stores or live?
- Are the source code, design files, servers and store accounts transferred to you by contract?
- Do they show a working demo every two weeks, with written scope and acceptance criteria?
- Are maintenance, scaling and GDPR/security costs written into the quote?
Copyright and trademarks
A business model and features are generally not protected on their own, but the Mint name, logo, interface design, content and source code are. That is why we build a product with similar functionality but your own brand, design and code. This is not legal advice; we recommend a trademark search before launch.
Frequently asked questions
How long does it take to build an app like Mint?
A first version with account linking through a licensed open banking provider, categorisation and budgets can ship in a few months. Categorisation quality improves over time with usage data.
What do I need to access bank data?
Account-information services need regulated authorisation in most markets. Integrating with a licensed open banking provider instead of obtaining a licence yourself is a faster and safer way to start.
Are there copyright or trademark issues?
The personal finance management business model is free to use, but the name, logo, interface design, content and code cannot be copied. This information is general in nature and is not a substitute for legal advice.
What should I look for when choosing a company to build a personal finance app?
Ask about experience with open banking integration, data security and machine-learning classification. The scope of security testing should be made clear.