SaaS / business softwareFintech & paymentsOriginal by iyzico
Payment providers like iyzico, a leading Turkish payment service provider, spare businesses in Turkey the trouble of signing a separate virtual POS agreement with each bank. A business accepts payments from all cards, in instalments and with 3D Secure through a single integration, and marketplaces split payments among their sellers automatically. On the buyer side, fast checkout with a saved card and buyer protection create trust. With ready e-commerce plugins, even small businesses start taking payments within minutes.
To build something similar, a payment institution licence and the capital, IT and audit obligations that come with it must be met first. On the software side you need a routing layer connecting to the virtual POS of several acquiring banks, an instalment and commission engine, card storage, marketplace sub-merchant management, settlement and reconciliation, a chargeback process, a merchant application flow and plugins for popular e-commerce platforms.
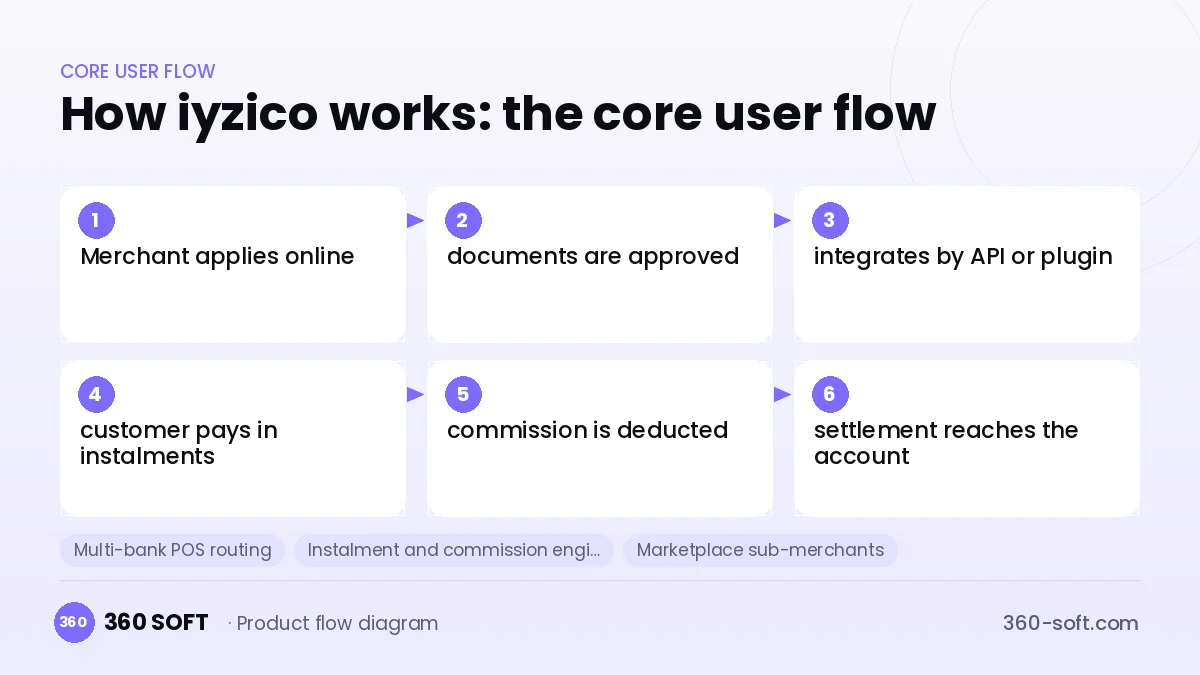
How iyzico works: the core user flow
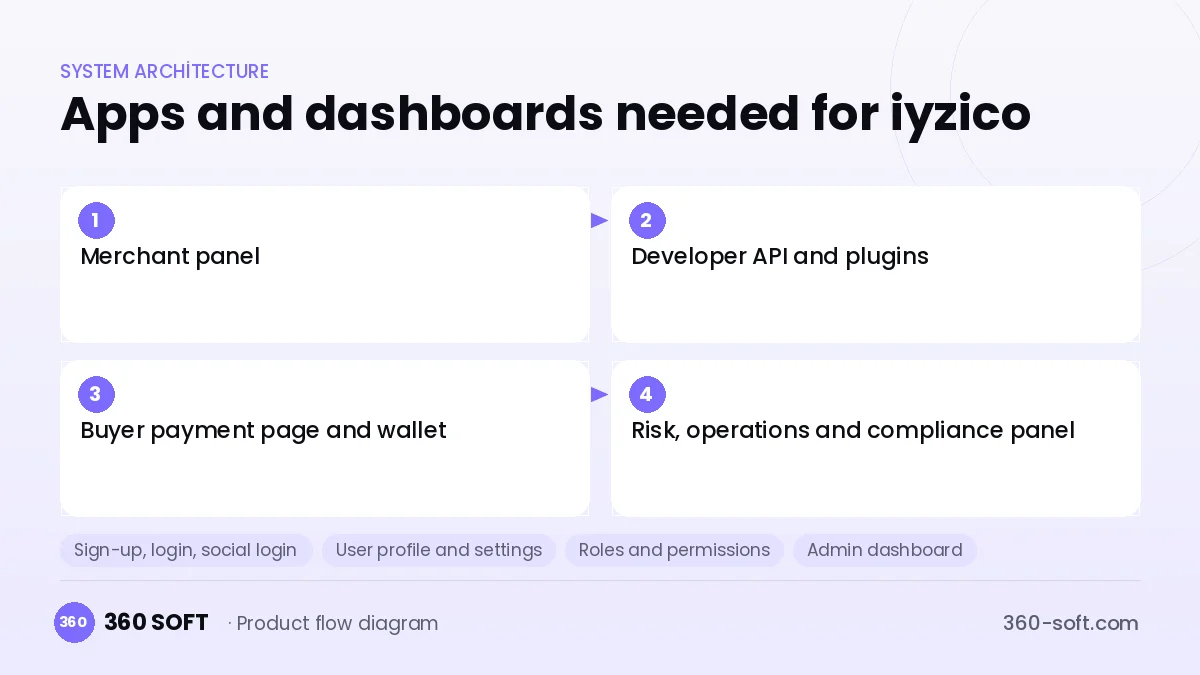
How many apps and dashboards do you need?
Merchant panel
Businesses manage their transactions, refunds, instalment commissions, disputes and settlement calendar.
Developer API and plugins
Developers integrate the payment page with the API, SDKs and ready e-commerce plugins.
Buyer payment page and wallet
Buyers pay with a card or saved account, see their orders and open protection claims.
Risk, operations and compliance panel
The team manages merchant approvals, suspicious transactions, bank reconciliation and regulatory reports.
Critical features of a product like iyzico
Multi-bank POS routing
A transaction is routed to the most suitable bank POS by card, number of instalments and cost, and falls back to a backup if one bank is down.
Instalment and commission engine
Instalment options and the cost of deferral are calculated per card programme, and the merchant sets who bears which instalment.
Marketplace sub-merchants
Sellers are registered as sub-merchants, and a single basket payment is split among them after commission is deducted.
Fast checkout with a saved card
Card details are stored tokenised, so buyers pay on different sites in one click and securely.
Digital merchant application
Company documents and signatory authority are uploaded, a risk score is calculated and suitable businesses go live quickly.
Buyer protection and dispute management
Buyer complaints and bank disputes reach the merchant with deadline tracking, and the result flows into settlement automatically.
What goes into the first version, what comes later
First version (MVP)
- Virtual POS integration with at least two banks, and 3D Secure
- Instalment and commission calculation
- A payment API, test environment and a basic e-commerce plugin
- Merchant panel and settlement reports
- Digital merchant application and risk checks
Later releases
- Marketplace sub-merchants and split payments
- A saved-card wallet and buyer protection
- Payment links and subscription collection
- Multi-currency and foreign card acceptance
Modules and how the budget is calculated
The budget is calculated with 360 SOFT’s pricing model from the modules below, about 34 screens and the project’s complexity: roughly 178 person-days for the full scope and 112 person-days for the first version. Every module you drop lowers the budget directly.
| Module | Phase |
|---|---|
| Sign-up, login, social login | First version |
| User profile and settings | First version |
| Roles and permissions | First version |
| Admin dashboard | First version |
| Online payments (Stripe / PSP) | First version |
| Subscriptions and recurring billing | First version |
| Email / SMS notifications | First version |
| Reporting and analytics | Later release |
| GDPR and security hardening | First version |
| Third-party API integration | First version |
| E-invoicing | First version |
| Marketplace integration (Amazon, etc.) | Later release |
Hosting, SMS, map APIs, app store accounts and payment-provider fees are separate items. Maintenance and improvements (optional): €600 / month. We send a fixed written price within 24 hours after a free discovery call.
The hard parts
Licensing and independent audit
A payment institution licence brings capital, IT audit, AML and GDPR obligations; this process is as long-running a project as the software itself.
Variety of bank integrations
Every bank's POS protocol, error codes and reconciliation files differ; a common abstraction layer and careful testing are needed.
Card security and fraud
Without PCI DSS compliance, tokenisation and real-time risk analysis, merchant and buyer trust cannot be earned.
Business model
Revenue comes from a per-transaction commission charged to merchants, with the rate varying by settlement term and sector. Extra products such as instalment deferral costs, early settlement, marketplace payment splitting, payment links and subscription collection enrich the model. High-volume merchants get tiered, negotiated pricing.
Get a free quote for your project
Let us scope it together and send a fixed written quote within 24 hours. NDA on request; you own the source code.
Choosing a company to build an app like iyzico
Most people searching “build software like iyzico” are really looking for a reliable app development company. When comparing quotes, check four things:
- Can you try similar products they have shipped, in the stores or live?
- Are the source code, design files, servers and store accounts transferred to you by contract?
- Do they show a working demo every two weeks, with written scope and acceptance criteria?
- Are maintenance, scaling and GDPR/security costs written into the quote?
Copyright and trademarks
A business model and features are generally not protected on their own, but the iyzico name, logo, interface design, content and source code are. That is why we build a product with similar functionality but your own brand, design and code. This is not legal advice; we recommend a trademark search before launch.
Frequently asked questions
How long does it take to build software like iyzico?
The core of POS routing, a payment API and a merchant panel can be developed within months. The licence application, bank agreements and security certification take longer.
Which licence is needed?
Collecting payments on behalf of merchants requires a payment institution licence from the national regulator; in Turkey that is the central bank. Without one, building a software layer on top of a licensed institution's infrastructure is an option.
Will there be copyright or trademark issues?
The payment institution business model is free to use, but the name, logo, interface design, documentation and code cannot be copied. This is general information, not legal advice.
What should I look for in a company that builds payment systems?
Choose a team that knows acquiring banks' POS protocols and has PCI DSS and IT audit experience. Ask how they verify reconciliation and settlement calculations.